
- Home
- /
- Core Business Performance
Core Business Performance
Attracting Deposits
The Bank operates the "Baspana" and "Tabysty" tariff programs, which allow the depositor to decide how many years they will save and at what interest rate they wish to receive a housing loan. At the same time, accumulation of 50% of the contract amount is required. The interest rate on savings is 2-5.5% per annum (EAR – up to 14-17.1% per annum, taking into account the state premium).
The monthly contribution amount is calculated such that, provided they are deposited evenly throughout the savings period, the customer will achieve the required value of the evaluation indicator by the end of the savings term. The value of the evaluation indicator increases when the depositor makes early payments during the initial stage of accumulation.
Deposits can be replenished using surplus funds from depositors' pension accounts. If a depositor of the Unified Accumulative Pension Fund has funds exceeding the sufficiency threshold, they can use lump-sum pension payments to replenish their deposit at the Bank for the subsequent receipt of loans to improve housing conditions.
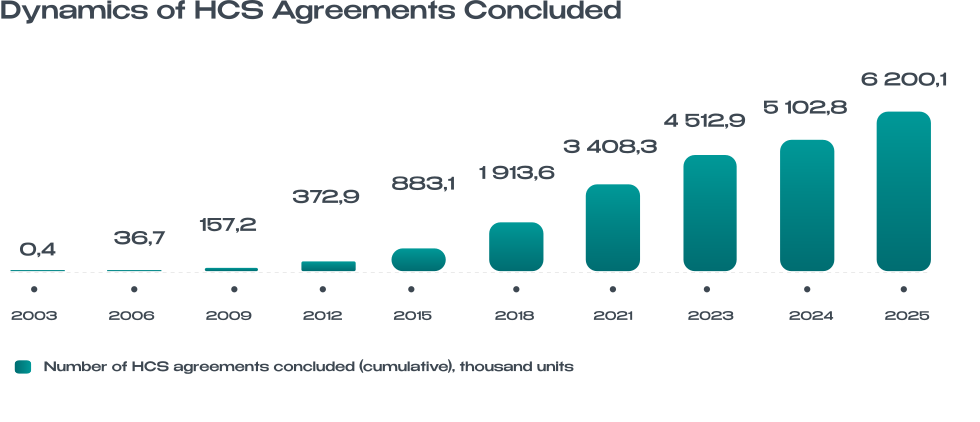
The pace of concluding contracts by the Bank shows a rapid, consistent increase in the population's participation in the development of the Kazakhstani housing construction savings system.
There is also a tariff program called the "State Educational Accumulative Deposit 'Aqyl'", which allows for the accumulation of funds to pay for the educational services of participating educational organizations, including foreign educational organizations implementing educational programs of technical and vocational, post-secondary, higher, and postgraduate education (the interest rate on the deposit depends on the base rate of the NBRK). The deposit agreement is concluded for a term of at least one year. Since the launch of the program, 158 thousand deposits have been opened (including 88 thousand over 2025), which indicates the high demand for this product among the population.
Issuance of Loans
The Bank provides its depositors with housing, intermediate housing, and preliminary housing loans to carry out measures aimed at improving housing conditions.
A housing loan is issued on the mandatory condition of accumulating the minimum required amount, complying with the accumulation period (at least 3 years), achieving the minimum value of the evaluation indicator established individually for the tariff program, confirming creditworthiness, and providing collateral sufficient to cover the issued loan amount. The loan term ranges from 6 months to 25 years, and the interest rates on the loan range from 3.5% to 5% per annum (EAR from 3.6% to 6.9%).
An intermediate housing loan is issued on the condition of early accumulation or a lump-sum payment of the minimum required amount (at least 50% of the contract amount) with subsequent lending within the contract amount, as well as upon confirmation of creditworthiness and the sufficiency of collateral. The loan utilization period is up to 25 years, and the interest rates on the loan range from 6% to 8.5% per annum (EAR from 6.2% to 9.6%).
A preliminary housing loan is issued within the framework of state programs and the "Svoy Dom" ("Your Home") Program. During the period of utilizing the preliminary housing loan, the borrower pays only the interest on the loan and simultaneously makes contributions to their deposit until reaching 50% of the contract amount. Upon expiration of the accumulation period, the accumulated savings and the housing loan are directed toward the repayment of the preliminary housing loan. The period for repayment and simultaneous accumulation under a preliminary housing loan is up to 8 years, and the interest rates on the loan range from 2% to 18% per annum (EAR from 2% to 24.3% per annum).
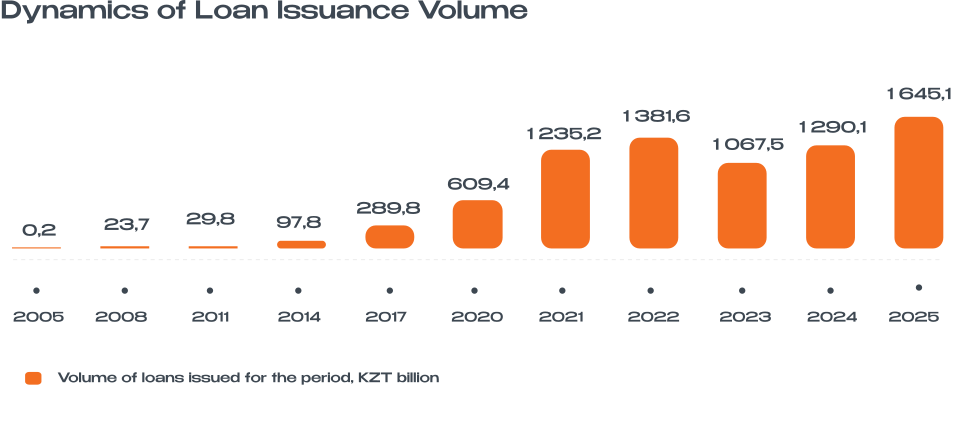
The Bank shows steady growth in loan issuance throughout its entire period of activity. The dynamic growth of the loan portfolio since 2012 is linked, in particular, to lending to the population under state and regional housing construction programs, as well as the Bank's own programs for each market segment.
Evaluation of Target Indicators
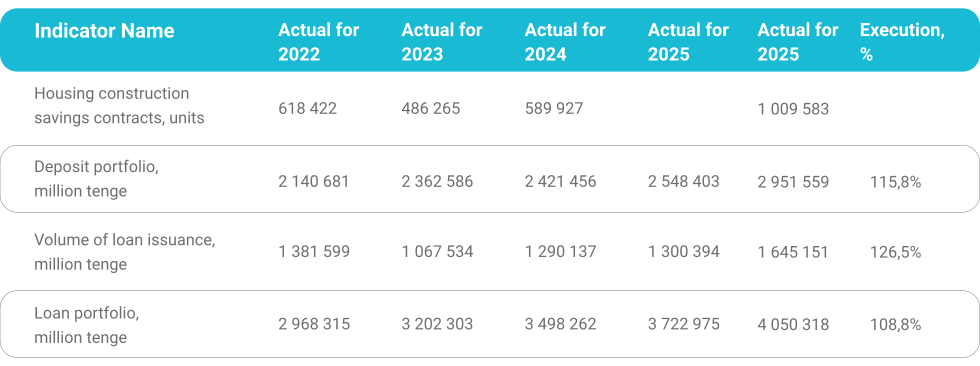
In total, over the entire period of its activity, the Bank has concluded 6.1 million contracts with a contract amount of Tenge 21.7 trillion. More than 3.5 million depositors have been attracted to the system with a deposit amount of Tenge 2.9 trillion. Otbasy Bank accounts for 37% of long-term deposits of the population. Otbasy Bank's share in the country's aggregate mortgage portfolio stands at 52%, which confirms its leading position in the market
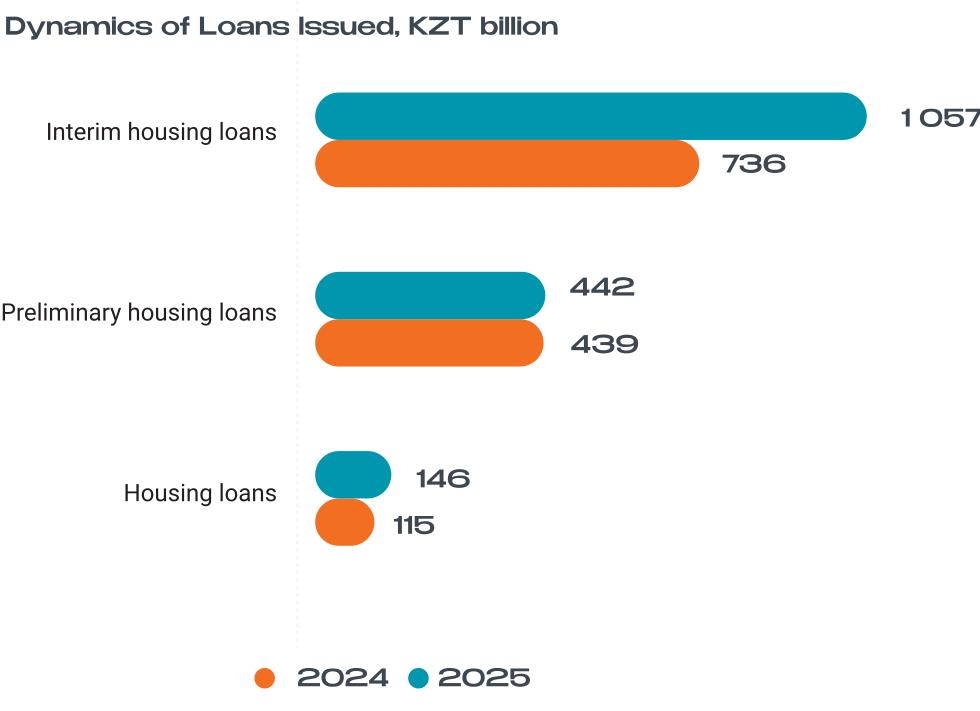
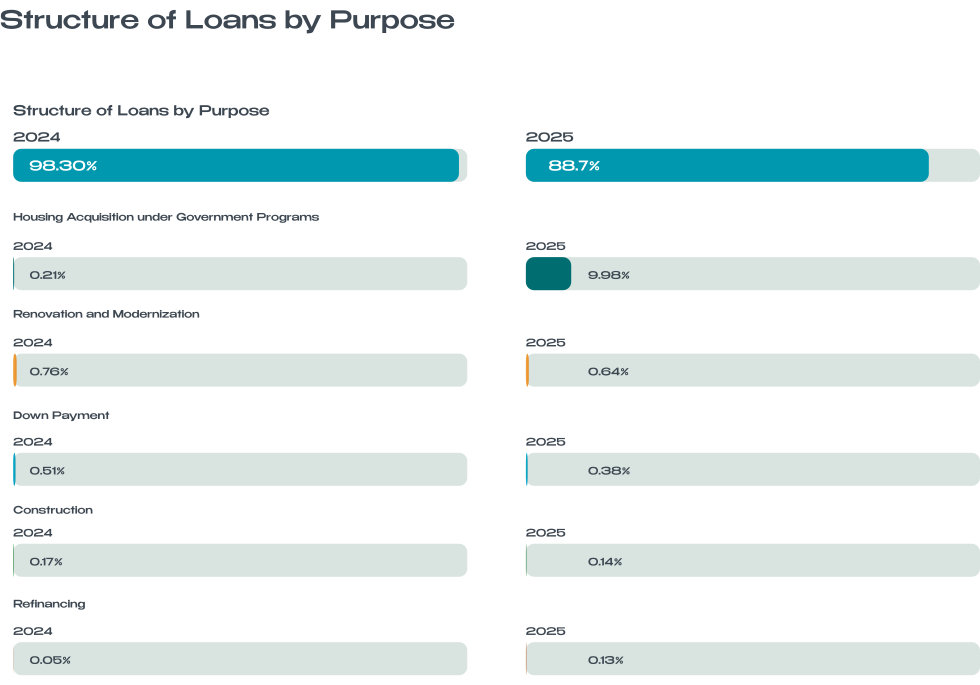
The Bank issues loans only to individuals. Intermediate housing loans based on the results of 2025 amounted to Tenge 1,057 billion. The volume of preliminary housing loans at the end of the year reached Tenge 442 billion. The volume of housing loans amounted to Tenge 146 billion.
An analysis of the Bank's key indicators over the period of the Development Strategy implementation demonstrates a steady positive dynamic in all major areas of activity, which indicates a high level of demand for the Bank's products among the population and its competitiveness in the financial market of Kazakhstan.
Implementation of State Housing Programs
The social well-being of citizens, primarily related to the housing issue, is recognized as a priority of our state's activity. To this end, various preferential housing programs are being introduced in the country, with special attention paid to socially vulnerable segments of the population. Otbasy Bank acts as the operator of such state housing programs. Over the past twenty years, Otbasy Bank has become a reliable ally for many Kazakhstanis in resolving their housing issues.
Over the entire period of its activity, the Bank has successfully implemented the state housing construction programs of 2005–2007, 2008–2010, and 2011–2014, the "Affordable Housing - 2020" program, the "Regional Development Program until 2020", the "State Program of Infrastructure Development 'Nurly Zhol' for 2015–2019", and the "State Housing Construction Program 'Nurly Zher'". To date, the specified programs have completed their operation.
In the reporting year, the Bank carried out the implementation of the "Concept for the Development of Housing and Utilities Infrastructure for 2023–2029" (hereinafter – the Concept). The Bank acts as the operator of the Concept and its directions – "2-10-20" and "5-10-20" – and provides loans to socially vulnerable segments of the population who are registered on the waiting lists of local executive bodies. Socially vulnerable segments of the population include, among others, persons with Group 1 and Group 2 disabilities, families having or raising children with disabilities, as well as large families and mothers, orphans or children left without parental care, and so on. Under the Concept, the Bank issues preliminary housing loans at interest rates of 2% and 5% per annum, depending on the citizen's category:
Of these, the applicants eligible for 2% per annum are:
- orphans and children left without parental care;
- large mothers decorated with "Altyn Alka" or "Kumis Alka" pendants, or who previously received the title of "Heroine Mother", as well as those decorated with the Order of "Maternal Glory" of the I and II degrees, and large families;
- persons with Group 1 and Group 2 disabilities;
- families having or raising children with disabilities;
- other categories of waitlist registrants participate in lending under the Concept at 5% per annum.
All participants of the Concept acquire housing built by local executive bodies using loan funds.
Since September 2025, the allocation of state housing by the Bank has been carried out within the framework of the Law of the Republic of Kazakhstan "On Amendments and Additions to Certain Legislative Acts of the Republic of Kazakhstan on Housing Policy Reform Matters" in the manner determined by the Rules for the Implementation of State Support Measures Aimed at Improving Housing Conditions (approved by Order of the Minister of Industry and Construction of the RK dated May 30, 2025, No. 187).
The Law on Housing Policy Reform expanded the list of categories with a priority right in the distribution of housing. Thus, the participants of preferential mortgage lending at 2% are recognized as:
- orphans and children left without parental care;
- large mothers decorated with "Altyn Alka" or "Kumis Alka" pendants, or who previously received the title of "Heroine Mother", as well as those decorated with the Order of "Maternal Glory" of the I and II degrees, and large families;
- persons with Group 1 and Group 2 disabilities;
- families having or raising children with disabilities;
- WWII veterans and persons equated to WWII veterans;
- combat veterans on the territory of other states;
- widows (widowers).
In general, in 2025, within the framework of state programs, 124 objects (8,519 apartments) with a total area of 723,645 sq. m totaling Tenge 92.8 billion were received for implementation.
As part of state programs (the Concept, state support measures aimed at improving housing conditions), 5,277 loans totaling Tenge 67.8 billion were issued to Kazakhstanis in 2025, including 3,477 loans totaling Tenge 44.9 billion at a rate of 5% per annum and 1,800 loans totaling Tenge 22.9 billion at a rate of 2% per annum. Loans under the "5-10-20" direction were issued using revolving funds. Under the "2-10-20" direction, the issuance of loans was carried out using the remaining budget funds allocated in 2023, as well as revolving funds. Lending in 2025 to persons with disabilities, orphans, as well as large families and families raising children with disabilities, was carried out using the specified funds.
In addition, during the reporting year, the Bank, acting as a national development institution, began performing the functions of allocating rental housing from the municipal housing stock (rental housing provided by local executive bodies).
To facilitate housing distribution under state support measures, local executive bodies transferred 8,519 apartments to the Bank, including 3,467 credit housing units and 5,052 rental housing units. Regarding credit housing, 940 apartments were transferred to local executive bodies for the execution of sale and purchase agreements, while processing has been completed for 357 apartments, and the housing has been handed over to citizens. As for rental housing, 1,324 citizens consented to receive housing, and the documentation for 1,151 of these apartments was forwarded to local executive bodies for the execution of lease agreements. Inventory procedures are currently ongoing for the remaining citizens.
Implementation of the Mechanism for Assigning and Making Payments to Certain Categories of Citizens for Housing Rented in the Private Housing Stock
In 2022, a program for subsidizing part of the rent for housing rented in the private housing stock was launched in Kazakhstan to support citizens registered with LEBs as in need of housing. Otbasy Bank acted as the operator of this program. In the reporting year, the Bank continued the implementation of this mechanism. In 2025, Tenge 9.7 billion was actually allocated, including Tenge 7.6 billion from the republican budget and Tenge 2.1 billion from local budgets. The volume of utilized funds amounted to Tenge 9.5 billion (Tenge 7.6 billion and Tenge 1.9 billion, respectively). The balance of unused funds was returned to the republican and local budgets, respectively. At the end of the reporting year, payments were made under 9,791 applications totaling Tenge 9.5 billion to large families, families raising children with disabilities, orphans, as well as individuals with Group 1 and Group 2 disabilities.
Implementation of the "With a Diploma to the Village" Program
Since 2023, the Bank has been implementing the state program "With a Diploma to the Village" ("S Diplomom v Selo"). Within the framework of the program, the Bank developed a remote application submission system for specialists in healthcare, education, social security, culture, sports, and the agro-industrial complex, as well as civil servants of the apparatuses of akims of villages, towns, and rural districts who have arrived to work and reside in rural settlements. Additionally, a personal account dashboard was created for local authorities to administer the submitted applications. To enhance customer service and increase the digitalization of public services, the process was fully migrated to an online format. This allowed specialists in education, healthcare, and the agro-industrial complex, as well as program administrators in local executive bodies, to save time when submitting and processing applications for subsidized budget loans intended for rural territory development.
In 2025, the Bank signed 183 units of commission agreements with local executive bodies for a total budget amount of more than Tenge 30 billion. In total, 9,917 loans amounting to Tenge 70 billion, as well as 17,513 lump-sum relocation allowances totaling Tenge 26 billion, have been issued under the program.
Implementation of Regional Programs
Regional programs are aimed at retaining and supporting specialists who are in high demand across the regions, such as doctors, teachers, journalists, athletes, cultural workers, and other professionals. Regional programs have been implemented since 2017 through the provision of repayable budget loans by local executive bodies to Otbasy Bank.
Otbasy Bank is actively working on the implementation of regional programs aimed at supporting youth in the regions of Kazakhstan. To date, youth programs are being implemented in all regions of the country, with the exception of the Akmola, Turkistan, and East Kazakhstan regions.
The total volume of financing for regional programs amounts to Tenge 272.4 billion (local akimats – Tenge 223.6 billion, Otbasy Bank – Tenge 48.8 billion). This includes the 2025 financing volume for regional programs, which stood at Tenge 83.9 billion (local akimats – Tenge 75.9 billion, Otbasy Bank – Tenge 8 billion).
The total funding for regional programs also includes youth programs, the budget for which amounted to Tenge 217.6 billion (local akimats – Tenge 179.2 billion, Otbasy Bank – Tenge 38.4 billion). This includes the 2025 financing volume for youth programs, which stood at Tenge 74.5 billion (local akimat – Tenge 68.5 billion, Otbasy Bank – Tenge 6 billion).
In 2025, 5,035 loans totaling Tenge 94.8 billion were issued within the framework of regional programs, of which 4,105 loans totaling Tenge 77.8 billion were issued under youth programs. This serves as a successful example of productive interaction between the Bank and the local executive bodies of the regions.
Implementation of the "Corporate" Program
Today, housing can be purchased not only by employees of state enterprises but also by workers of private companies—factories, manufacturing enterprises, medical institutions, and other organizations interested in supporting their staff. Within the framework of the Year of Working Professions, special attention was paid to expanding opportunities for representatives of working specialties and developing partnerships with employers. To reduce the social burden on the budget and retain youth in the regions, the Bank proposes that large companies consider cooperation under the "Corporate" ("Korporativny") program on an annual basis.
In total, the total amount of funding under the "Corporate" product reached Tenge 5.6 billion. This includes Tenge 757.3 million allocated in 2025 to develop cooperation with a number of companies, including NJSC "Yessenov University" (Caspian University of Technology and Engineering named after Sh. Yessenov), "LS Group" LLP, "Quantum TECH School" LLP, "FSSA" LLP, and others.
Overall, within the framework of the "Corporate" program, the Bank helped improve the housing conditions of 281 company employees for a total amount of Tenge 4.1 billion, including 56 loans issued in 2025 for a total amount of Tenge 709.7 million.
Implementation of the "Askeri Baspana" Program for Military Personnel
The military program is also one of the Bank's high-demand products. As a source of funding, the Bank attracts funds in the market on market terms, and also utilizes its own funds. To date, Otbasy Bank is the only bank where special deposits have a distinct status and a guarantee of immunity.
Within the framework of implementing the Action Plan to Ensure Macroeconomic Stability and Mitigate the Negative Consequences of Economic Reforms, approved by the Prime Minister of the Republic of Kazakhstan O.A. Bektenov on October 17, 2025, the Bank resumed the provision of preliminary housing loans to housing allowance recipients under the previously operating "Askeri Baspana" program. Furthermore, the "Nauryz Askeri" direction was launched within the "Nauryz" program for housing allowance recipients.
In 2025, 11,709 loans totaling Tenge 207.2 billion were issued to housing allowance recipients within the framework of current programs. This includes 32 loans totaling Tenge 1.2 billion issued under the "Nauryz Askeri" direction during the period from November to December 2025.
Implementation of the "Green Mortgage" Ecological Program
Since the beginning of 2023, the Bank has been implementing Kazakhstan's first "Green Mortgage" ("Zelenaya Ipoteka") program for the purchase of apartments in energy-efficient residential complexes built according to "green standards," thereby supporting the strategic initiative to promote environmentally friendly housing. The program is oriented toward protecting the health of citizens and the environment.
The main condition for implementing the program is the compliance of the acquired housing with a "green standard" certified under one of the existing systems in Kazakhstan (OMIR, GOST R, BREEAM, LEED), regardless of its certification level.
This means that the developer uses eco-friendly and environmentally safe materials when building houses, landscapes and greens the territory, ensures all houses are placed thoughtfully, enables air temperature adjustment in apartments, provides transport accessibility, etc.
To date, the Bank cooperates with 25 developers across Kazakhstan who comply with ecological construction standards, having concluded memorandums with them. The Bank plans to continue actively developing cooperation in this direction. In 2025, 570 loans amounting to Tenge 14.7 billion were issued.
Attracted Funds
For the full-scale activity of the Bank, as well as to ensure the fulfillment of obligations to depositors regarding the issuance of housing loans to them, the Bank utilizes its own funds, funds allocated from the state budget and the budgets of local executive bodies, client deposits, and funds attracted in the financial market (issuance of debt securities, loans from various organizations).
Over the entire period of its activity within the framework of state and regional programs, the Bank has attracted budget funds in the amount of Tenge 972 billion. As of January 1, 2026, Tenge 948 billion or 97.5% of the total volume of attracted funds has been utilized (taking into account revolving funds, Tenge 1,181 billion or 121.42% of the total volume of attracted funds).
In 2025, the Bank placed social bonds on the trading floor of JSC "Kazakhstan Stock Exchange" for a total amount of Tenge 282,017,183,000 (in nominal terms) within a yield range of 16.49–18.00% per annum.
Sales System
The Bank's activity is characterized by relatively high growth rates, as evidenced by the growth of key indicators. This dynamic is significantly ensured by the successful work of the Bank's sales system, which includes branches, service centers and outlets, consultants and agents (organizations providing agent services to the Bank under concluded agency agreements), internet banking, video banking, etc.
Key Participants in the Bank's Sales System
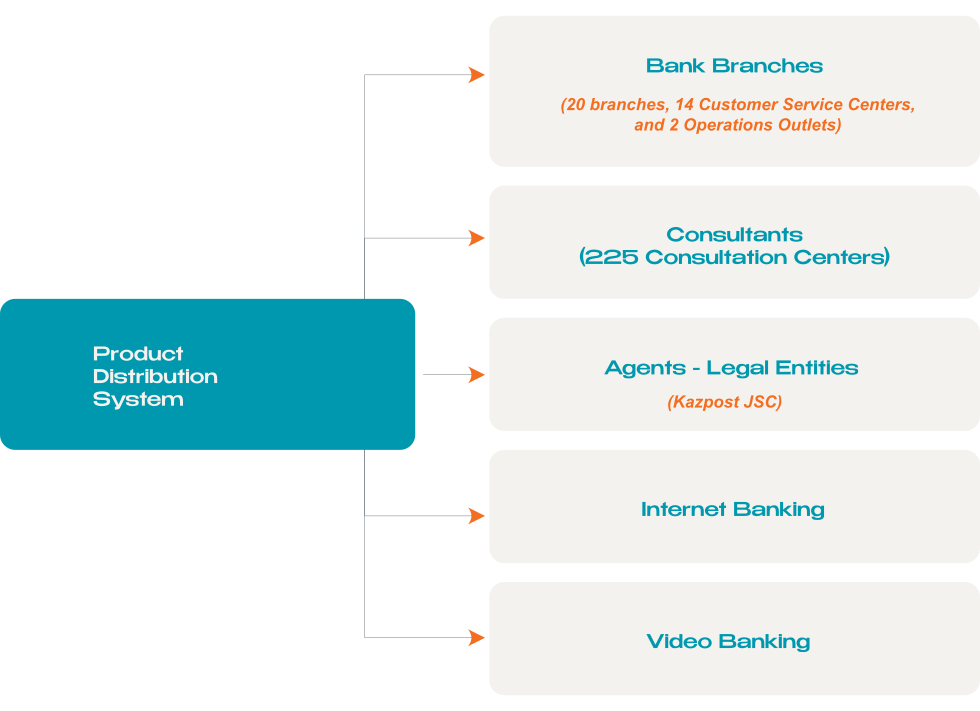
The Bank strives to create an infrastructure where clients can access products and services in a manner that is most convenient for them—meaning at a convenient time, in a convenient place, and through a convenient method.
To this end, the Bank has deployed the following service channels for its clients:
- Bank branches (branches, service centers, service outlets, call center);
- Bank consultants (consultation centers, mobile/field service);
- Consultant operators (digital guides) in Bank branches to assist with receiving services via remote channels;
- Consultant operators (postal carriers) providing support in receiving services through remote service channels;
- Corporate agent: JSC "Kazpost";
- Video banking;
- Internet banking;
- The Bank's mobile application;
- Bank partners (Kaspi.kz, Electronic Government of the Republic of Kazakhstan, JSC "Halyk Bank of Kazakhstan", JSC "Bank CenterCredit").
As well as communication channels:
- The Bank's corporate website;
- Quanysh-AI chat-bot (WhatsApp and Telegram messengers, inside the mobile application, and chat-bot widgets on the Bank's websites: hcsbk.kz, otbasybank.kz, enpf-otbasy.kz);
- The Bank's official social media pages (Instagram, Facebook, VKontakte), among others.
In 2025, the Bank continued to develop digital technologies and customer services. By the end of the reporting year, 5.3 million customer transactions were processed, with the share of transactions conducted via remote channels breaking down as follows:
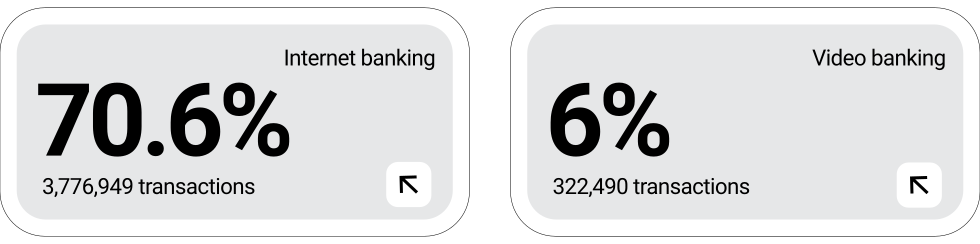
Based on the 2025 results, the Bank's branches processed 444,491 transactions, representing 8% of the total volume. The agent network executed 804,472 transactions in 2025, accounting for 15% of total transactions. The Customer Satisfaction Index (CSI) for service in Bank branches reached 4.82 points for 2025.
For reference: The Customer Satisfaction Index (CSI) for service in the Bank's branches is measured in accordance with the Bank's Methodology for working with CSI and NPS service indicators at JSC "Otbasy Bank".
Special Services for Particular Categories of Citizens
Out of care for its clients, including low-mobility groups and citizens with disabilities, the Bank has established the following service conditions and accommodations:
- Mobile/Field service organized via the Bank's independent consultants. Equipped with mobile tablets, the Bank's consultants can service clients at any location convenient for the customer.
- Sign language interpretation integrated via video services to enable seamless servicing of deaf and hard-of-hearing clients.
- Priority service arranged in Bank branches allowing persons with disabilities to be served out of turn.
- Infrastructural accessibility across Bank branches, including the installation of ramps, elevators, and tactile paving equipped with a staff call button, among other adaptive solutions.
- Both online and in-person training sessions were conducted to strengthen the Bank employees’ competencies in providing respectful, effective, and inclusive services to customers with disabilities. The training covered topics such as "Guidelines for Respectful Communication with Persons with Disabilities," "Serving Customers with Disabilities: Key Considerations," and "Adapting Banking Services for Persons with Disabilities."
- All Bank branches are listed on the Ministry of Labour and Social Protection of the Population of the Republic of Kazakhstan's Information Portal "Social Protection of Persons with Disabilities" (https://inva.gov.kz/).
To ensure convenient and accessible banking services for all customers, including persons with disabilities and individuals with reduced mobility, the Bank has implemented the following measures:
- An outreach banking service has been established through the Bank's field consultants. Using mobile tablets, consultants are able to provide banking services at any location convenient for the customer.
- Banking services for deaf and hard-of-hearing customers are available through a video remote sign language interpretation service.
- Customers with disabilities are entitled to priority service at all Bank branches.
- Bank branches are equipped with ramps, elevators, tactile paving, staff assistance call buttons, and other accessibility features to ensure a comfortable and barrier-free customer experience.
- Annual training for Bank personnel on servicing clients with disabilities. These educational events focus on enhancing front-office competencies regarding respectful and effective communication, specific service requirements, and the adaptation of banking products. In 2025, this training was completed by 640 branch front-office employees, 1,111 agent network consultants, and 44 administrator-guides.
- Accessibility transparency maintained by placing detailed information regarding entrance accessibility and services for persons with disabilities and low-mobility groups on the Bank's official website (hcsbk.kz), the Information Portal of the Ministry of Labor and Social Protection of the Population of the RK ("Social Protection of Persons with Disabilities" at https://inva.gov.kz/), and within the "2GIS" navigation application.
In 2025, the Bank issued 469 loans to clients with disabilities for a total amount of Tenge 6.2 billion.
Contact Center
The Bank places great emphasis on receiving feedback from clients, striving for effective development in the interest of its customers. The Bank receives feedback through written communications (received by courier, postal mail, e-mail, and the Bank’s website) and oral communications (received by telephone and during direct client visits to the Bank). The acceptance of submissions, if any, is performed on a daily basis.
Customer Service Development Department with AI
Since 2020, the Bank has been actively introducing innovative technologies to improve customer interactions. One of the key tools has become the "Quanysh" chat-bot. This modern tool functions in popular messengers such as WhatsApp, Telegram, and Instagram, as well as in the bank's mobile application, providing clients with a convenient and prompt method of communication.
In 2025, the Bank achieved the following results:
- 3.7 million chats with clients were processed.
- The configured chat-bot successfully resolved 98% of inquiries without the need to involve operators.
- The average response time of the chat-bot was 3–4 seconds.
- 3,550,019 incoming calls were processed. The configured IVR successfully handled 60.40% of calls without requiring operator assistance.
Artificial Intelligence Development: Strategy and Achievements
On March 20, 2025, the Bank launched the intelligent chat-bot "Quanysh-AI"— a virtual assistant built on the basis of artificial intelligence technologies.
"Quanysh-AI" advises depositors and borrowers on all products and services of the bank on a round-the-clock basis (24/7). It is integrated into the Otbasy Bank mobile application and is also available in WhatsApp and Telegram messengers and on the Bank's websites—hcsbk.kz, otbasybank.kz, and enpf-otbasy.kz—ensuring instant connection with the Bank without waiting for an operator's response.
Clients can address the bot with both text and voice messages in the Kazakh and Russian languages. This makes the service as convenient and accessible as possible for all categories of users. An AI module has been implemented in the "Otbasy Info" section (the "Frequently Asked Questions" block) on the hcsbk.kz website: answers are generated online, ensuring that clients are provided with up-to-date information.
Thanks to the deployment of artificial intelligence, modernization of digital platforms, and improvement of customer service, the Bank has taken a significant step toward innovative development. The new Quanysh-AI chat-bot has become not only a convenient tool for clients but also an example of how technology helps increase the quality and accessibility of financial services. All of this confirms the Bank's commitment to its strategic goals and values.
Furthermore, to ensure data security and the integration of AI with the Bank's internal systems, the following were developed:
- a data provisioning system to handle confidential information when working with cloud-based LLM models;
- a data encryption system allowing the integration of the new Quanysh-AI chat-bot with the Bank's databases.
The chat-bot provides clients with access to more than 40 personal data items across 7 main areas, including:
- personal data;
- information on deposits;
- information on special accounts for housing allowance recipients;
- information on account attachments/freezes;
- information on the utilization of UAPF (CPF) funds;
- information on applications for participation in the rental housing subsidy program;
- information on loans;
- information on the status of support tickets.
Remote Sales Department
In accordance with the implementation of strategic objectives regarding the comprehensive transition of the Bank's activities, business processes, competencies, corporate culture, and business models into a digital Bank—maximizing the use of digital technology capabilities—the Bank is conducting work to develop and implement innovative products using new technologies to build a new experience. Thus, a video banking service has been operating at the Bank since 2020. In 2021, work was carried out to enhance this service—a new feature for remote customer service was launched: online deposit opening via a video call.
In addition, within the framework of further accessibility of the Bank's products, an online mortgage scheme via a concierge service through video banking was implemented. This product combines the best service practices of live communication and digital channels—Phygital. The implementation of this functionality helped the Bank's clients apply for mortgages remotely and reduced branch visits to a minimum, which was particularly relevant in the epidemiological environment. Over 2025, 10,736 loan applications worth Tenge 288 billion were processed. Video calls helped save time for the Bank's clients and allowed them to receive services remotely for post-deposit operations. This feature was utilized 543 thousand times.
Department of Client Analysis and Remote Sales Development
With the aim of expanding the deposit portfolio, as well as executing target indicators in 2025, the Department conducted more than 290 marketing campaigns, which resulted in inflows totaling Tenge 294 billion. More than 587 operational campaigns were prepared and launched for the operators of the Remote Service Department, resulting in the opening of 72 thousand deposits and the processing of 10.7 thousand loans.
At the end of the year, a large-scale marketing campaign titled "State Premium 2025" was conducted. The total number of campaign participants exceeded 2.2 million clients, who replenished their deposits by a total amount of Tenge 454.2 billion. In the course of the campaign, more than 265 thousand participants replenished their deposits by 200 MRP to reach the maximum state premium value (Tenge 157,280).
Within the framework of CRM development, 35 updates were implemented to populate the CRM client profile with data, allowing the Remote Service Department operator to work on a "single-window" principle. Furthermore, functionality was expanded for the preparation and execution of marketing and operational campaigns.
At the end of 2025, work was carried out to modernize the TSA-VIDEOBANKING system, implementing 12 user/client enhancements, and system upgrades were conducted to improve operability, optimize, and accelerate processes.
Within the framework of the project for Big Data / Data Governance implementation, the following tasks were completed:
- a report was created in Oracle BI to display the results of calculations performed by analytical models;
- data analysis was conducted, and data mart maps were developed for the subdivisions of the business block;
- a pilot project was launched to implement solutions in the field of business analytics and big data processing;
- a list of measures for implementing the Data Management Strategy for the business block was approved;
- the Temporary Data Governance Concept for the business block was approved.
Responsible Lending and Financial Products
The Bank conducts its lending activities by providing credit products across all regions of the Republic of Kazakhstan. The primary focus of the Bank's lending operations is the provision of credit products to its clients. The Bank provides the following types of credit products to HCS (Housing Construction Savings) depositors:
1) Housing loans;
2) Intermediate housing loans;
3) Preliminary housing loans.
Credit products are provided on standard terms for all clients of the Bank in the national currency of the Republic of Kazakhstan. Loans are issued to HCS depositors on the basis of housing construction savings agreements and bank loan agreements (housing loans, intermediate housing loans, preliminary housing loans) concluded with them in accordance with the Bank's internal regulations on loan issuance and the Bank's tariff programs.
Lending terms for the Bank's clients regarding credit products are determined by the provisions of the tariff program selected by the client. The utilization periods, interest rates, methods of securing performance under loan repayment obligations, and other baseline conditions for the Bank's credit products and services are established by the tariff programs and other internal regulations of the Bank.
The Bank's interest rate for providing a credit product is determined by the provisions of the HCS agreement. Bank loan agreements must explicitly specify the loan repayment method chosen by the borrower from among those offered by the Bank as of the conclusion date of the bank loan agreement. The interest rate on the loan is set at the time of concluding the housing construction savings agreement and remains fixed throughout the entire term of the agreement. The fixed interest rate is not subject to unilateral modification. Upon the initiative of an HCS depositor to switch from one tariff program to another, the fixed interest rate on the loan may, by mutual agreement of the parties, be adjusted downward or upward during the term of the HCS agreement, provided its conditions are met and in accordance with the legislation of the Republic of Kazakhstan and the Bank's internal regulations.
In bank loan agreements, the Bank specifies the full list of commissions and other fees, as well as their amounts, to be levied in connection with the issuance and servicing of the loan under the concluded agreement.
The Bank reserves the right to charge commissions and other fees but adheres to a policy of minimal tariffs for its services. This approach is aimed at maximizing the recruitment of new clients into the housing construction savings system and contributes to expanding the client base.
In 2025, the following changes occurred in the tariff system:
- the commission for reviewing loan applications was eliminated;
- the commission for early termination of a housing construction savings agreement and withdrawal of savings by foster children of orphanages was eliminated.
The Bank publishes information on rates and tariffs for banking and other services provided to individuals and legal entities on its website.
Credit Portfolio and Financing Indicators (SASB)
In order to increase the transparency of disclosure regarding lending activities, the Bank additionally discloses indicators stipulated by the SASB industry standards for commercial banks and mortgage finance.
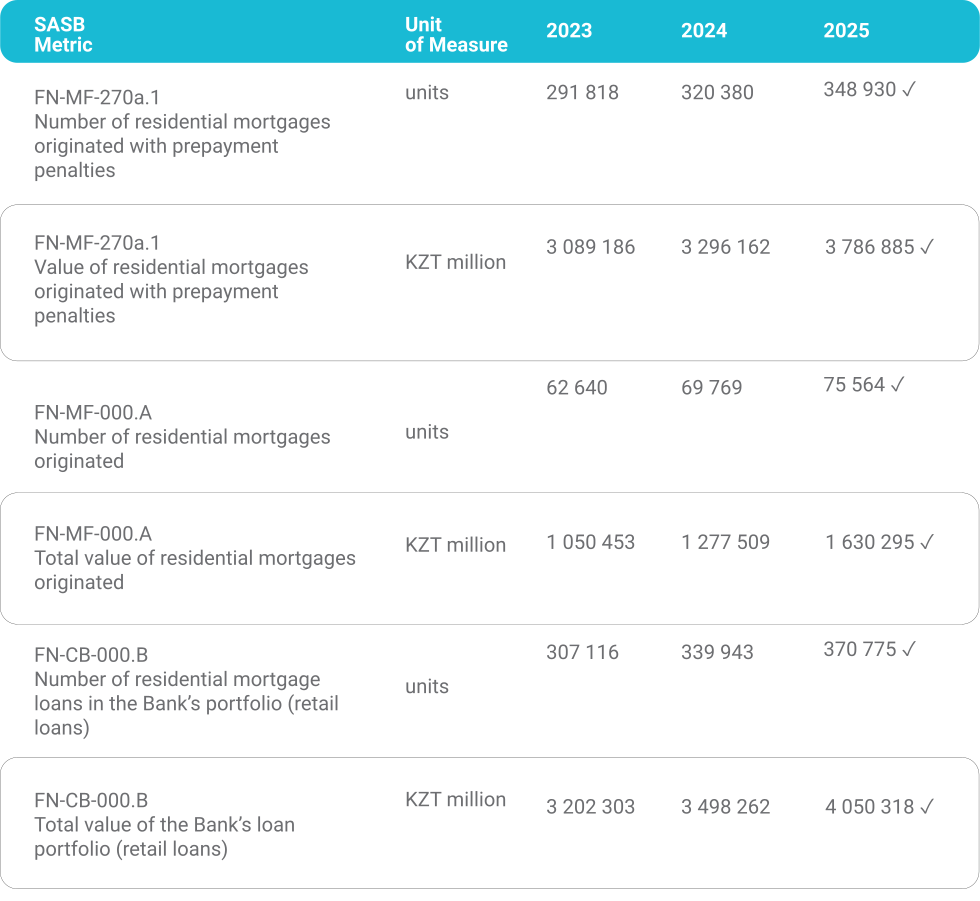
Detailed information on these indicators, including calculation methodologies and additional disclosures, is presented in the SASB index appended to this Report.
In 2025, the Bank continued to conduct various events and information initiatives aimed at informing clients about the importance of a responsible approach to personal data, promoting prudent financial behavior among the population, raising financial competency levels, and educating clients of various age groups on financial literacy matters.
Advertising and PR Activities of the Bank
The Bank popularizes the housing construction savings system by informing the population about available opportunities to purchase housing on favorable terms. An important component of this work is the implementation of comprehensive PR initiatives aimed at improving the financial literacy of Kazakhstanis and raising awareness of the Bank's products and programs.
In 2025, 10,061 publications mentioning Otbasy Bank appeared in the mass media. The press service prepared and distributed 96 press releases dedicated to products, services, and initiatives. Following their placement in the media, 700 earned (free-of-charge) materials were published.
Responses to media inquiries were prepared, resulting in the publication of explanatory materials regarding the Bank's products and the outcomes of the HCS system implementation on major news portals such as Kursiv.kz, Kapital.kz, inbusiness.kz, BES.media, Tengrinews.kz, krisha.kz, informburo.kz, and inform.kz.
The results of a marketing study showed that 86% of the total number of respondents trust the Bank. The Bank's brand awareness grew to 92.4%, while the customer satisfaction rate was maintained at 96.2%.
Thus, in 2025, the press service ensured a systematic presence of the Bank in the information landscape. Communications were structured around large-scale state and social initiatives, focusing on transparency, accessibility, and the clarification of new conditions for housing programs and the bank's products.
One of the priority areas in 2025 was the communication support for the launch and implementation of the new "Nauryz Zhumysker" direction. Extensive coverage of the results of this initiative, featuring stories of happy new homeowners, was secured in national media. Additionally, a significant volume of communications was directed toward explaining the new "Keleshek" voluntary savings system. As part of this effort, a series of materials was prepared to explain the program's conditions, benefits, and long-term value for citizens. This facilitated a clear and trust-based perception of the new product and established its strong association with Otbasy Bank.
To clarify the bank's new role as a national development institution, a dedicated information page was developed and launched on Nur.kz, a popular portal among Kazakhstanis. The page explained the principles of housing waitlist management, selection criteria, priority categories of citizens, and housing allocation mechanisms in an accessible format. Six articles were published in support of this project. This format made it possible to reach a broad audience and increase awareness among waitlist registrants.
Special attention was paid to engagement with expert and business media. Throughout the year, the Bank's executive management appeared on news programs on national television. An interview with Lyazzat Ibragimova, Chair of the Management Board, was organized for the Forbes portal, focusing on the bank's performance results for 2025. An expert interview with Galiya Smagul, Director of the Internal Audit Department, was also published, highlighting the role of internal audit in ensuring the bank's stability.
The conference titled "Housing Construction Savings: Best Practices and Strategic Leadership in Various Regions" stood out as a significant international event. It was organized by the Bank with the support of the International Union for Housing Finance (IUHF) and the European Federation of Building Societies (EFBS). The press service provided extensive coverage of the event, with publications appearing in more than 20 national and industry media outlets. Kazakhstan was presented as a platform for international dialogue on housing policy, which enhanced the bank's image on a global scale.